Stock refurbishment dominates upcoming pipeline, Cotai retains absolute growth leadership while economy-tier accommodation remains a persistent structural gap
This data-driven feature maps every confirmed, under-construction and pipeline hotel project in Macau for 2026Q4 to 2028Q3, breaking down supply distribution across Cotai and the Macao Peninsula, and highlighting the unaddressed economy-tier lodging gap that is reshaping the city’s hospitality market dynamics.
Macao’s hotel market is entering a new phase of measured supply expansion over the next 24 months (2026Q4 to 2028Q3), with baseline projections pointing to 3,600 to 5,000 new rooms entering the market, according to cross-referenced official data from the Macau Statistics and Census Service, Land, Public Works and Transport Bureau and public disclosures from major local resort operators.
This new supply wave stands in sharp contrast to the market conditions of two years ago. The city’s total current hotel room inventory sits at roughly 45,000 keys, around 1,800 rooms below the all-time high of 46,946 recorded in April 2024. This contraction is not a sign of market weakness, but the direct result of widespread targeted renovation projects across existing properties.
A representative example is the former 330-key Hard Rock Hotel at City of Dreams, which ceased operations in 2021 for a full rebrand, and re-entered the market earlier this year as the 149-suite REM Universe, delivering a far higher average daily rate while creating a net reduction of 180 standard rooms.
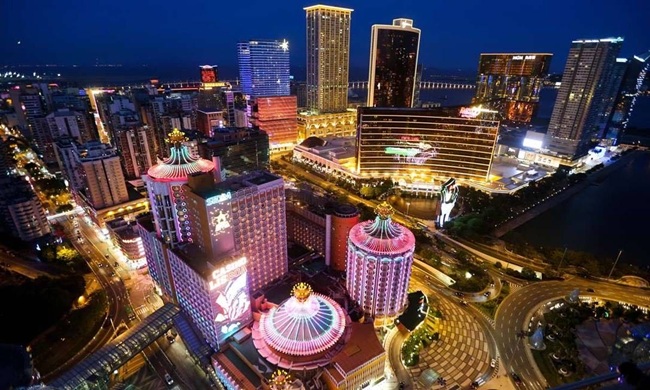
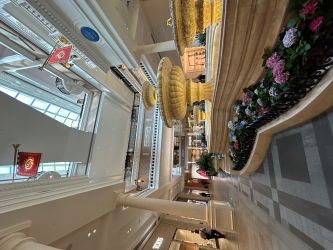
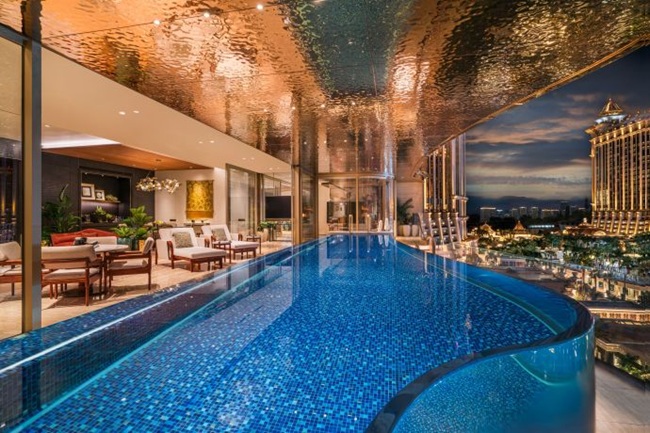
The upcoming pipeline is overwhelmingly concentrated in Cotai’s five-star resort cluster. Outside of the 1,600 new rooms from Galaxy Phase 4, new supply will come from the remaining undeployed phases of The Londoner, the final opening tranches of Grand Lisboa Palace, and the long-awaited Lisboa West Wing refurbishment project. Almost no new rooms are coming from entirely greenfield land development, meaning 90% of this new inventory is the product of upgrading and repositioning existing hotel assets.
Beyond the projects set to launch in the next two years, Macao’s longer-term hotel project pipeline shows 27 developments currently at the design and approval stage, with a combined projected inventory of 16,700 rooms. 12,615 of these future keys belong to just five Cotai-based resort expansion projects, confirming that the district will remain the unchallenged core of new hotel supply well past 2028.
A clear structural split defines the market across different geographic zones. Cotai continues to lead with large-format, high-investment new builds and expansions. The Macao Peninsula, by comparison, will see almost no entirely new hotel properties, with all upcoming supply limited to the renovation and repositioning of existing mid-to-high-end historic properties. The most notable gap in the market remains the economy-tier accommodation segment, which currently only comprises 44 properties with a combined 1,200 rooms, an extremely small share of the total inventory that has failed to keep pace with the rapid growth in budget and family visitor arrivals.
Even with this new supply wave coming online, Macao’s long-term average hotel occupancy has remained stable near 90%, as diversified MICE, leisure and regional visitor demand continues to absorb new inventory far faster than most regional peer destinations. (Reported by Building.hk)
Building.hk Data Note
All supply figures in this report are cross-referenced against official public records disclosures from Macao’s Land, Public Works and Transport Bureau, with unannounced project room counts marked as projected estimates for industry reference.